DSCR loans vs. hard money
One is for the flip or the rehab, the other is for the hold. Most investors end up using both, in that order.
Use hard money for a short project: a flip, or the buy-and-rehab phase of a BRRRR deal, where you need fast funding and plan to be out within six to eighteen months. Use a DSCR loan for the hold: a rent-ready property you intend to keep for years on a 30-year fixed rate.
Key differences at a glance
| Feature | DSCR loan | Hard money |
|---|---|---|
| Typical use | Long-term rental holds | Fix-and-flips, BRRRR acquisitions |
| Loan term | 30-year fixed available | 6–24 months |
| Rate | Market rate, 30-year money | Often 10–15% and up |
| Points and fees | About 1–2 points | 2–5 points |
| Property condition | Rent-ready required | Distressed is fine; rehab funded |
| Closing speed | About 30 days | Days to two weeks |
| Prepayment | Optional; lowers rate and costs | Usually none |
| Payments | Fully amortizing | Interest-only is common |
The BRRRR connection
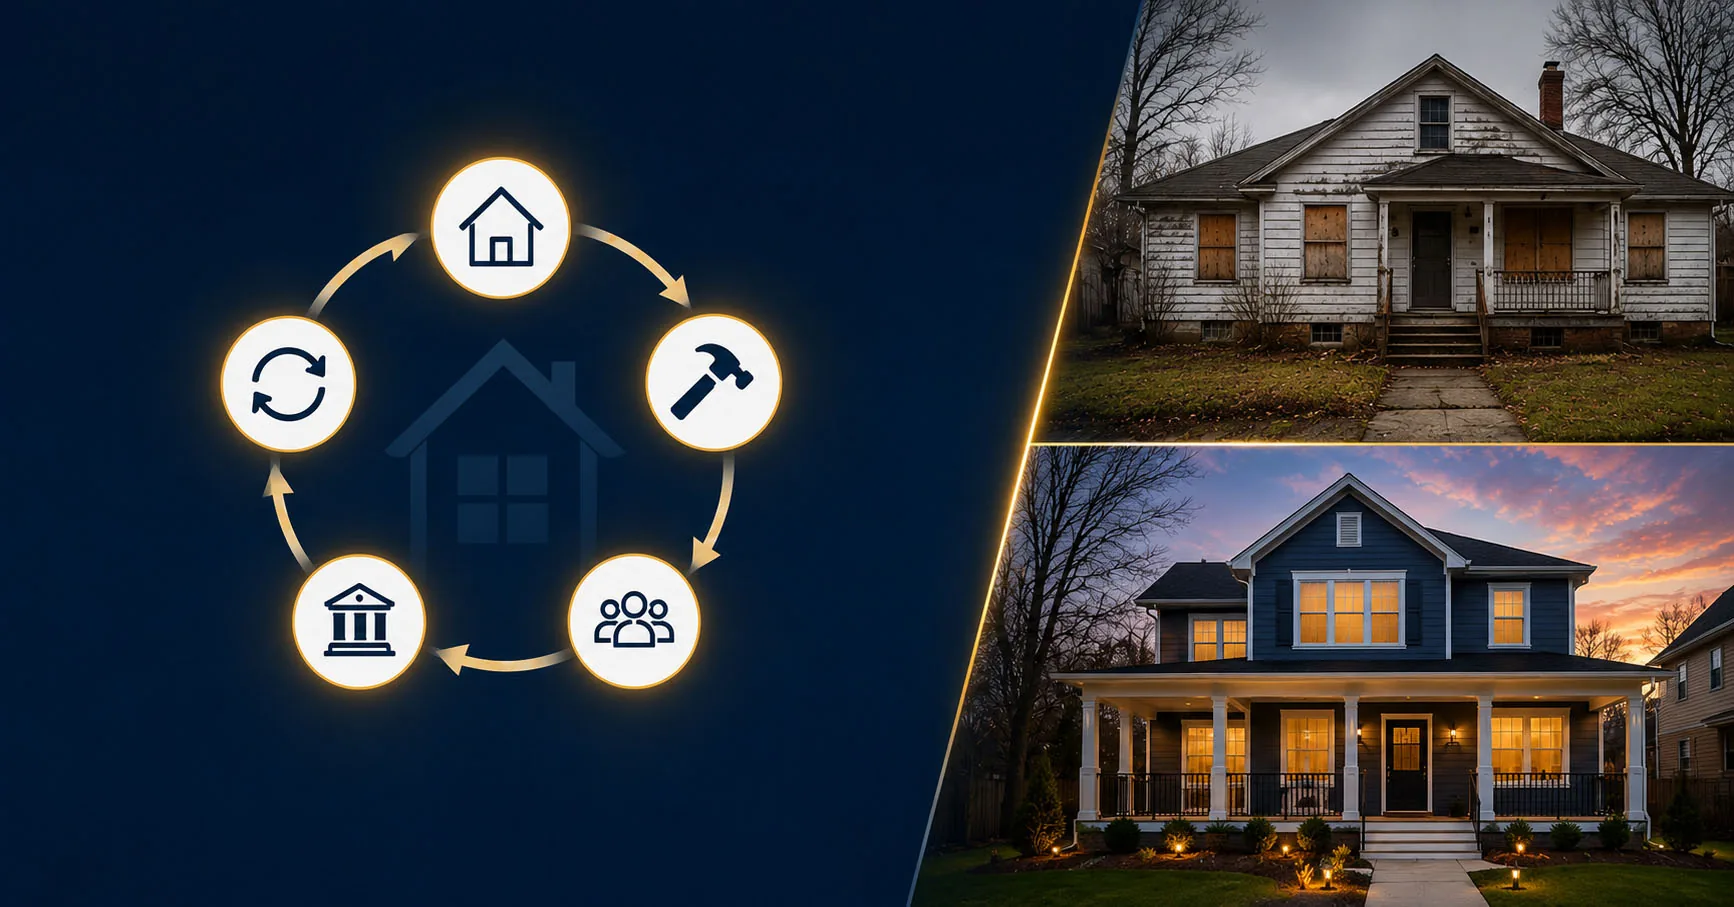
Buy, Rehab, Rent, Refinance, Repeat uses both loans in sequence. Hard money gets you in; the DSCR loan gets your capital back out.
- 1
Buy and rehab with hard money
Fast close on a distressed property. Rehab costs rolled into the loan, interest-only while you renovate.
- 2
Finish the work and place a tenant
Get the property rent-ready and leased. The lease and the new value are what the next loan is underwritten on.
- 3
Refinance into a DSCR loan
Pay off the hard money with a 30-year DSCR loan at the new appraised value and take the forced equity out in cash. No income documents.
- 4
Repeat with the recovered capital
The cash-out funds the next deal. Scale without raising new money every time.
The investor recovers nearly all of the $330,000 they put in, keeps a cash-flowing duplex, and the recovered capital funds the next one.
Use a DSCR loan for…
- Buying rent-ready or turnkey property
- Long-term buy-and-hold
- Refinancing out of hard money after the rehab
- Cash-out refinances on stabilized rentals
- Predictable 30-year payments
Use hard money for…
- Fix-and-flip projects
- The acquisition and rehab phase of BRRRR
- Distressed property that needs real work
- Closing in days, not weeks
- Bridging until the permanent loan
Hard money is expensive by design. On a flip that clears $50,000–$100,000 it is a cost of doing business. It is never a loan you want to hold, which is exactly why BRRRR investors refinance into DSCR once the property is stabilized.
DSCR loans vs. hard money: FAQs
Yes, and it is one of the most common uses. After the rehab is done and a tenant is in place, investors refinance out of the high-interest hard money loan into a 30-year DSCR loan. That is the “refinance” step of BRRRR.
You typically need both. Hard money funds the purchase and rehab because it closes fast and covers renovation costs. Once the property is stabilized you refinance into a DSCR loan for the long hold.
DSCR loans need the property rent-ready at closing. If it needs significant work, use hard money or a rehab loan first, then refinance into DSCR when it is done. Minor cosmetic repairs are usually fine.
Most DSCR programs want three to six months of ownership before a cash-out refinance at the new value. A rate-and-term refinance that just pays off the hard money may be available sooner. Your advisor structures the timing.
Not sure which fits? Ask Greg.
Describe the property and the plan. You get a recommendation, not a pitch.
Or call 609-992-5356 to reach Greg directly.
DSCR and Non-QM loans are arranged through third-party providers. Guidelines shown are typical program parameters and vary by program, property and borrower profile; your advisor confirms the terms for your scenario. This is not a commitment to lend. All loans subject to credit approval. Advisors Mortgage Group, LLC · NMLS #33041 · Equal Housing Opportunity.
Not sure if this program fits you? Ask — it is free.
A licensed local advisor compares your options and tells you what you qualify for. No obligation, no impact to your credit.